All Categories
Featured
Understanding Your Benefits of IUL Policies
As you compare Medicare Supplement insurance coverage strategies, think of how much treatment you require, how often you go to the doctor and how much you can afford to pay towards your medical expenses yourself. Each Medigap strategy has a various level of coverage, so you ought to find one that fits your specific requirements.
With Initial Medicare (Components A and B), you're accountable for paying approximately 20% of your healthcare facility bills. Medigap prepares pay for some or all of your remaining costs, depending upon your plan letter. The very best Medicare Supplement prepare for you depends on your health and budget. Leading strategies Part A coinsurance Yes Yes Yes Part B coinsurance Yes Yes Yes Blood transfer (3 pints) Yes Yes Yes Part A hospice care Yes Yes Yes Proficient nursing facility Yes Yes Yes Part A deductible Yes Yes Yes Part B deductible Yes Part B excess charges Yes Yes Yes = 100% Other plans Part A coinsurance Yes Yes Yes Yes Yes Yes Yes Part B coinsurance Yes Yes Yes Yes 50%75% Yes Blood (3 pints) Yes Yes Yes Yes 50%75% Yes Part A hospice care Yes Yes Yes Yes 50%75% Yes Proficient nursing center Yes Yes 50%75% Yes Part A deductible Yes Yes Yes 50%75%50%Part B deductible Yes Part B excess chargesForeign travel emergency80%80%80% Yes = 100% This can provide you comfort since you won't be amazed by high medical expenses.
Strategies F and C have much better protection than Strategy G, however you can't get them if you're a brand-new enrollee. Plus, these strategies might not conserve you cash since of their high monthly rates. Insurance provider can use your health history if you get a plan outside the six months around your 65th birthday, called the "initial registration duration." If you buy a strategy with low protection when you're 65 and later on decide to update to something much better, such as Strategy G, business might quote you a high rate or reject you coverage completely.
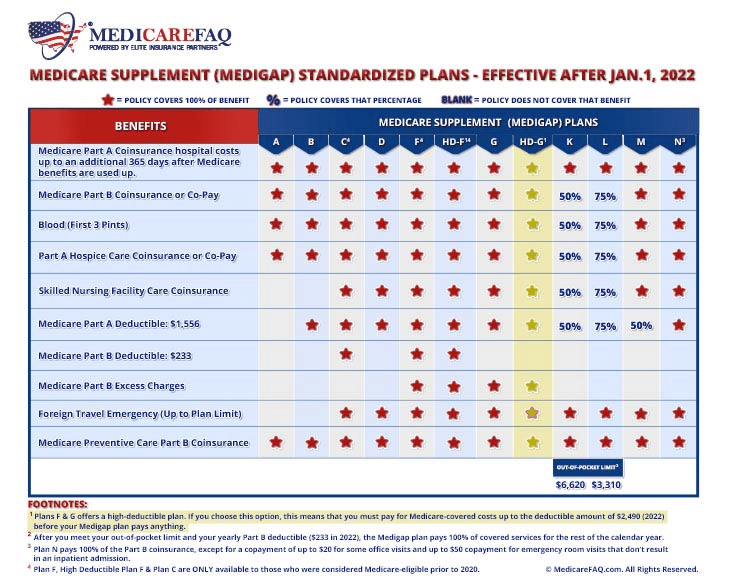
Plan G has the finest coverage for the majority of elders and others on Medicare. After you pay this, Strategy G will spend for treatment such as doctor sees, blood tests or outpatient medical treatment. Advantages and disadvantages of Plan G Popular strategy that covers nearly all of your health costs Often a much better worth than Strategy F Rates can be costly, at $180 each month, usually More affordable plans may be a better offer if you hardly ever check out the doctor Strategy F has the finest coverage of any Medigap strategy in general.
Pros and cons of Strategy F Pays for nearly all medical costs High regular monthly rates Not available to brand-new Medicare enrollees Strategy N has similar coverage to Plan G but expenses less. With Strategy N, you have to pay $20 for medical professional visits and $50 for journeys to the emergency situation room.
Insurance in Lakewood CAFinding the Best 2026 Medicare Supplement Plans
Pros and cons of Strategy N Yes Covers nearly all of the costs you're responsible for with Medicare Yes Plan N costs about $137 each month, which is $43 each month less than Strategy G Additional costs you're responsible for paying when you visit the medical professional could counteract savings You may have extra costs if your doctor does not accept the prices set by Medicare High-deductible Strategy G has the most affordable month-to-month rate of any Medigap policy.
Keep in mind, companies can charge greater rates or deny coverage because of your health history if you change Medicare Supplement plans outside the 6 months around your 65th birthday. That indicates you may be stuck to a high-deductible Strategy G when you're older and in worse health, costing you more in the long run.

This means that Medicare Supplement Strategy G from AARP/UnitedHealthcare provides you the exact same protection as Strategy G from Aetna, Blue Cross or any other company.

Latest Posts
Financial Stability Strategies Through Term Life Insurance

Navigating Medicare Part D
Navigating EPO Networks for Better Family Health Coverage